Together Loans

Screenshots
Details
- Rating
- 272.00 reviews
- Version
- 9.1.2
- Developer
- Transform Credit Inc
Analysis by Norviv
When a loan becomes part of a household budget, the difficult part is often not remembering that it exists. It is keeping the right person informed about payments, checking the current account details, and avoiding a last-minute search through emails or paperwork. I tested Together Loans with that everyday problem in mind, and I found it most useful as a focused mobile place for managing an existing loan rather than as a general finance app.
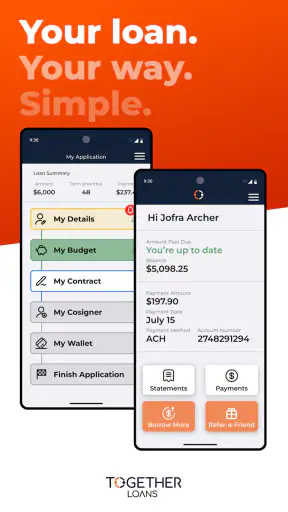
Together Loans is a free finance app from Transform Credit Inc. Its purpose is narrow, which is both its main strength and the first thing a new user should understand: this is built around managing a Together loan, not around replacing a full banking app, household budget planner, or credit-monitoring service. The app is rated for Everyone, runs on Android 7.0 or later, and its current version is 9.1.2.
The app has reached over one hundred thousand installs, with an average rating of 4.3 from more than six hundred ratings and over two hundred reviews. Those figures suggest that it has found a practical audience, but they do not change the central question I would ask before installing it: do you already have a Together loan to manage? If the answer is no, there is little reason to make this part of your financial routine.
How Together Loans fits into a shared household routine
When a loan affects more than one person’s monthly plans, I find it helps to separate account access from household coordination. This section looks at how a borrower can use a dedicated loan app as a private checkpoint, then bring only the useful details into a shared budget conversation. That distinction matters even more when the household’s routine involves a shared device or one person handling the bills.
A useful companion when one person handles the loan
In many households, one person is the named borrower while another person still needs visibility into the monthly plan. That can happen when partners divide bills, when an adult child helps a parent organize finances, or when a couple simply wants to avoid relying on one person’s inbox. In that situation, a dedicated loan app can be easier to use than opening a general banking application and hunting through unrelated transactions.
I would use Together Loans as a quick checkpoint before a household money conversation. The borrower can open the app, review the relevant loan information, and then discuss the next payment or the remaining plan with the other person. That workflow is more sensible than passing around a banking password or leaving sensitive paperwork on a shared device.
There is an important boundary here: the app should be treated as the borrower’s account space, not as a shared household wallet. A partner may help with budgeting, but that does not automatically make them an account holder. I would avoid handing over login credentials simply for convenience. If two people need to coordinate, the safer habit is for the borrower to check the app and communicate only the information needed for the household decision.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
What the app is—and what it is not
The store summary describes Together Loans as a way to manage a loan in one place. In practical terms, that makes it a focused account-management tool. I would not choose it as my main place for tracking groceries, rent, utilities, savings goals, or several unrelated lenders. Those tasks belong in a banking app, spreadsheet, or budgeting service that is designed to combine many financial sources.
This narrow scope can actually make the app less intimidating for someone who dislikes complicated financial dashboards. A borrower who only wants to deal with one loan may prefer a dedicated screen over a crowded banking application. The trade-off is that household members still need another method for seeing the complete monthly picture. Together Loans can support a conversation about one commitment, but it does not replace a complete household budget.
A realistic shared-device example
Imagine a couple using one tablet in the kitchen for household administration. One partner is responsible for the loan, while both people review bills on Sunday evening. I would not leave the loan account open on that tablet between sessions. Instead, the borrower could open the app when needed, check the relevant details, close the session, and record the agreed payment information in the couple’s private budget system.
That approach keeps the app in its proper role. It helps the borrower access the loan account without turning a shared device into an open financial file. It also prevents a common mistake: assuming that because a device is shared, every financial account on it should be shared too. The app is convenient for access, but convenience should not erase account boundaries.
Setup should begin with ownership, not convenience
Before installing, I would decide who actually needs the app. If you are the borrower, the answer is straightforward. If you are a family member helping with finances, the better starting point is to clarify what you need to know and whether the borrower can share that information directly. Installing the app on someone else’s phone does not by itself create a legitimate reason to access their loan account.
I would also choose the device carefully. A personal phone is preferable for a financial app because it is less likely to be passed between children, guests, or relatives. If a household uses a shared Android device, I would make sure the screen is locked whenever the app is not being actively used. These are simple habits, but they matter more for a loan account than they would for a recipe or shopping-list application.
The minimum operating-system requirement is Android 7.0, so the app remains available to people using older Android devices that still meet that requirement. I would still check that the phone receives security updates and has enough storage for ordinary app updates. Compatibility allows installation, but it does not make an old, unsupported device a good place for sensitive financial access.
The first useful test after installation
After installing, my first test would not be exploring every screen. I would confirm that the correct borrower can sign in, that the loan information is recognizable, and that the app gives enough clarity for the specific task the household wants to perform. If the goal is simply to check a payment detail, there is no benefit in building a complicated routine around the app.
I would then decide where household notes belong. The app should remain the private account-management space, while shared planning can happen in a separate place that does not expose sign-in details. This separation is one of the most useful practical distinctions I took from using a dedicated loan app: account access and household coordination are related, but they are not the same activity.
Coordination without turning the app into a group account
Shared finances often fail because people confuse access with communication. One person may need to know how a loan affects the month’s budget, but that does not mean everyone needs direct access to the account. I would use Together Loans to confirm the borrower’s information, then discuss the household impact verbally or through a private budgeting method.
A helpful routine is to agree on a regular review moment. For example, the borrower can check the account before the household’s bill-planning session and bring only the necessary details to that discussion. This reduces repeated logins, avoids passing the phone around, and makes it easier to spot whether the loan fits alongside other commitments.
Another useful habit is to keep a clear distinction between confirmed information and estimates. If someone says, “the loan is covered this month,” that may mean money has been set aside, not that a payment has already been processed. I would use the app to verify the account-specific detail and use the household budget to track the money reserved for it. Mixing those two records can create false confidence.
Where the focused design helps
The focused design is valuable when a borrower wants a direct route to loan management. There are fewer unrelated financial distractions than in a full banking app, and the purpose is easy to understand. For someone who checks a loan occasionally rather than managing investments, multiple cards, and savings accounts, that simplicity can be reassuring.
I also think the dedicated format works well for households in which only one loan needs shared attention. A general finance app may require linking accounts, categorizing transactions, or maintaining a larger financial profile. Together Loans is a better fit when the immediate task is narrower: keep track of the Together loan and make it part of a sensible payment routine.
Where the focused design becomes limiting
The same narrow purpose can feel restrictive for a user who wants a complete financial overview. If you are comparing several loans, planning debt repayment across different lenders, or trying to understand total household spending, this app will not be the only tool you need. I would choose a broader budgeting solution for those jobs and keep Together Loans for the account it is designed to manage.
I would also avoid expecting it to solve communication problems inside a household. A dedicated account app cannot decide who should pay, how a couple should divide expenses, or whether a relative should be allowed to see private financial information. Those decisions need a conversation and clear boundaries. The app can support the process, but it cannot replace agreement between the people involved.
Age, trust, and the meaning of an Everyone rating
The Everyone content rating is useful context for families because it indicates that the app is presented as suitable for a general audience. I would not interpret that as permission for children to use a parent’s loan account. Age suitability and account authority are different things. A young person may be able to install an app, but that does not mean they should handle a borrower’s credentials or payment decisions.
For an older relative, the app may be helpful if they are the borrower and want a direct way to manage their own account. I would offer assistance with installation or navigation without taking control of the account. The best arrangement is usually one where the account owner remains the person making decisions, while a trusted helper assists only with the device or explains what is on screen.
Trust also matters between adults. I would not install the app secretly on a partner’s phone, use another person’s unlocked device to inspect the account, or save access details in a place where the whole household can see them. Financial transparency should be agreed upon, not created by quietly expanding access.
Choosing Together Loans over usual alternatives
Compared with a mobile banking app, Together Loans is more specialized. A bank app usually gives a broader view of balances and transactions, which is better for day-to-day spending and overall cash flow. Together Loans is the more natural choice when the loan itself is the item you need to manage and you do not want it buried among unrelated accounts.
Compared with a spreadsheet, the app should be more convenient for checking the loan account itself, while a spreadsheet remains better for household forecasting. A spreadsheet can show how the loan interacts with rent, food, school costs, and savings, but it cannot serve as a substitute for the borrower’s account access. I would use both only if the household genuinely needs both levels of detail.
Compared with paper statements or email searches, the app offers a more direct routine for a borrower who prefers a phone. Paper can be useful for records, and email can preserve a history of correspondence, but neither is as convenient for a quick account check. Still, I would not delete important documents simply because the app is installed. Digital convenience and record keeping serve different purposes.
Small workflow improvements that make a difference
My first practical tip is to make the app part of a scheduled money check rather than opening it repeatedly throughout the week. A single planned review is less stressful and makes the information easier to use in context. The borrower can check the account, update the household budget, and then close the app.
Second, I would keep household notes free of sensitive sign-in information. If a partner needs to know the amount to reserve for the month, record that planning detail separately from passwords, security answers, or account identifiers. This lets the household coordinate without turning a shared notes app into a second set of credentials.
Third, I would review the app after an update instead of assuming that every screen behaves exactly as before. The current release is version 9.1.2, and keeping an app current is sensible for access and maintenance. At the same time, a household that relies on a particular screen should confirm that its routine still works after updating, especially before an important payment-planning session.
Finally, I would decide in advance what happens if the borrower changes phones or loses access to the usual device. The app can be part of the routine, but it should not be the only place where the household knows that a loan exists. Keep the broader budget organized and make sure the account owner knows how to regain access through the appropriate official route.
Who should install it, and who should skip it?
I recommend Together Loans to an existing borrower who wants a dedicated mobile way to manage that loan. It is also a sensible choice for a household where one person owns the account but needs a simple, repeatable process for bringing the loan into shared budget discussions.
I would skip it if you are looking for a complete money-management system, a way to combine several lenders, or a shared family finance dashboard. I would also skip it if you do not have a Together loan, because the app’s value depends on that specific relationship. In those cases, a banking app or broader budgeting tool is likely to be a better starting point.
My household verdict
After using Together Loans, I see it as a practical specialist rather than an all-purpose finance companion. Its free price removes a common barrier to trying it, and its focused role makes sense for borrowers who want their loan management kept separate from everyday spending. The developer, Transform Credit Inc, has positioned it around a clear need, and the strong user response gives it reasonable credibility for people considering the same workflow.
My recommendation comes with one condition: treat it as a private account tool that supports household coordination, not as a shared family account. Use it on the borrower’s device when possible, check the loan during a planned budget review, and keep wider household planning somewhere designed for that job. With those boundaries, the app can make one important financial responsibility easier to organize.
For the right user, that is enough. I would install it if I had a Together loan and wanted a straightforward mobile routine. I would not expect it to manage the rest of my financial life, and I would not use it to bypass a conversation about trust or responsibility. Its best quality is its clear, limited purpose: helping the borrower keep one loan within reach while leaving the household’s broader decisions where they belong.
Frequently Asked Questions
01What is Together Loans, and what does the app offer?
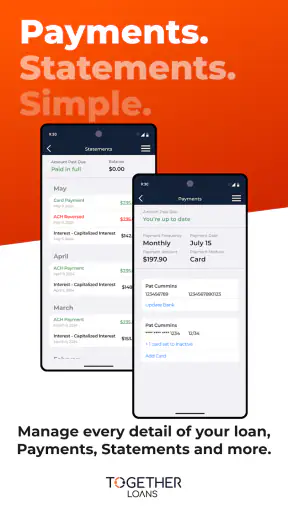
Together Loans is a loan-related service designed to help users explore borrowing options and manage the application process through a digital platform. Depending on your location and eligibility, it may provide access to personal-loan information, application forms, repayment details, and communication with the lender or broker. Available products, rates, and features can vary, so review the official terms carefully before applying.
02Can I apply for a loan through Together Loans?
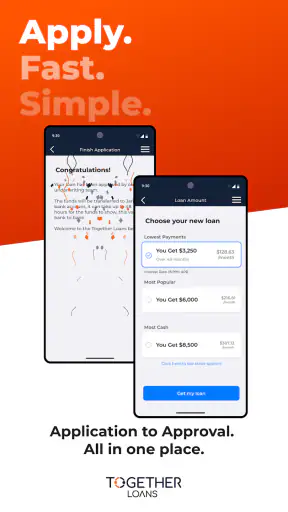
The platform may allow eligible users to submit a loan request or application online, but approval is not guaranteed. You will generally need to provide personal, employment, income, and banking information so your eligibility and affordability can be assessed. Before submitting anything, check whether Together Loans operates in your country, confirm the identity of the actual lender, and read all fees, interest rates, and repayment conditions.
03What information and documents might Together Loans require?
During the application process, Together Loans may request details such as your full name, address, date of birth, employment status, income, regular expenses, and bank information. Additional documents could include proof of identity, proof of address, or evidence of income. Providing accurate information is essential because incorrect details may delay assessment or affect the decision. Only upload documents through the official, secure platform.
04Are there fees or risks associated with using Together Loans?
Loan applications can involve interest, arrangement charges, late-payment fees, or other costs depending on the lender and product selected. Some services may be free to use while the lender charges the borrower separately. Always calculate the total amount repayable rather than focusing only on the advertised monthly payment. Never pay an upfront fee to an unverified party, and avoid borrowing unless the repayments comfortably fit your budget.
05Is Together Loans safe, and what should I check before downloading or applying?
Before using Together Loans, download it only from an official app store or access the verified website, and check the developer or provider details, privacy policy, permissions, and customer-support information. Confirm that the service is authorized to operate in your region and understand how your data will be shared. Read independent reviews and the full loan agreement, and remember that no legitimate service can guarantee approval without an affordability assessment.


